The action item: build a dedicated soft-cost contingency and reconcile invoices every month, since soft costs are the category most likely to blow past your original estimate.
- Owners should build a separate soft-cost contingency and reconcile invoices monthly, as soft costs can significantly exceed initial estimates and cause cash-flow issues.
- Soft costs, which often range from 20% to 35% of total budgets, include permits, legal fees, design, financing, and project management, and tend to extend beyond project completion.
- Soft-cost overspending can accrue quickly due to delays in permits, extended legal or design fees, and interest costs on financing, especially when timelines stretch beyond initial schedules.
- Lenders verify hard-cost draws through site inspections tied to milestones, while soft-cost draws rely on paid invoices and signed milestone documentation, requiring proactive package submissions.
- Proper classification, detailed documentation, separate contingencies, and monthly reconciliation help control soft costs and prevent overruns from undermining project profitability.
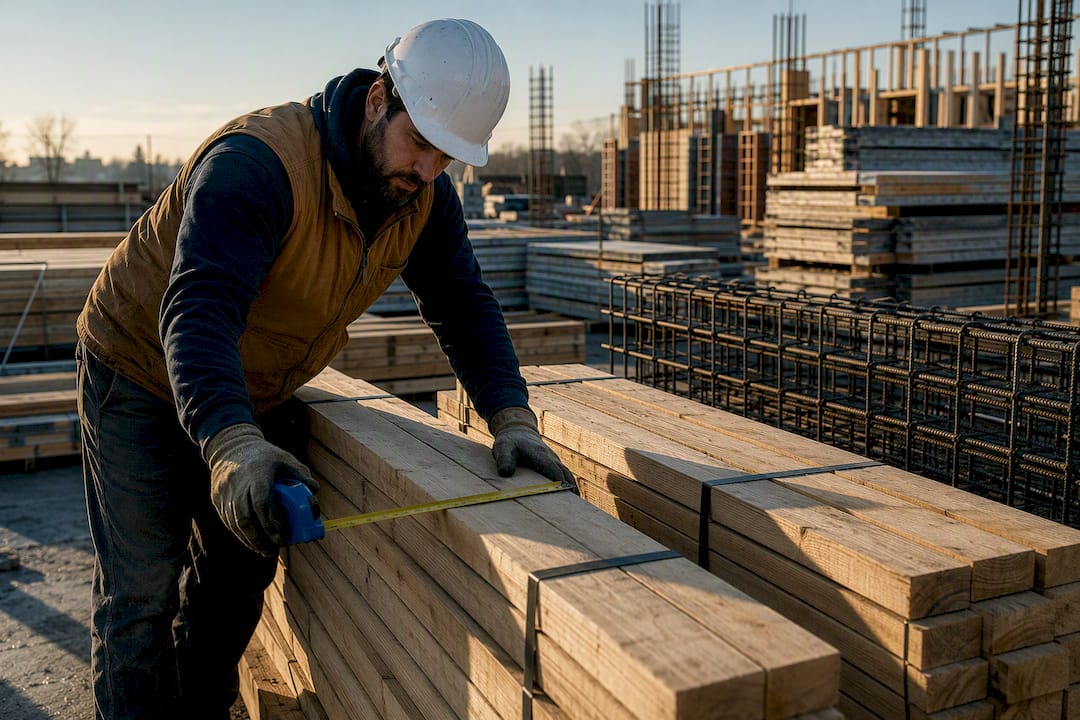
Hard costs are easier to estimate than almost anything else in a project budget, because they attach to a quantity and a unit rate. You know how many square feet of drywall you need, what a framing crew charges per hour, and what steel costs this quarter. That predictability is exactly why lenders lean on hard costs as the backbone of their draw schedules.
Hard costs cover the physical build, start to finish:
Variance still happens, and it happens for predictable reasons. Labor rates shift with regional demand, material prices swing with inflation cycles, unexpected site conditions (rock, contamination, poor soil) force redesign, and scope changes add square footage or upgrade finishes mid-build. A well-run estimate accounts for all four.
Three habits improve accuracy. First, price everything by unit rate rather than lump sum, so you can isolate which trade is driving overruns. Second, request a full schedule of values from your general contractor before you sign anything. Mixing the two reserves is how owners end up short on both.

Soft costs are the non-physical expenses that make construction possible: design, permitting, financing, insurance, legal work, and project administration. Construction cost research describes them as moving targets, and that framing is accurate. They start before a shovel touches dirt and, in several cases, continue well after the building is finished.
Here’s a working construction soft costs list covering the categories owners underestimate most often:
Preconstruction soft costs front-load your spending, often involving specialized software architects use to develop designs and feasibility studies. Architects, engineers, and consultants typically get paid before a permit even exists. What surprises most owners is what continues after the ribbon-cutting: final legal closeout fees, extended insurance premiums if the schedule slips, and lease-up marketing that can run for months after a certificate of occupancy. Research on soft costs puts the typical soft-cost share at 20% to 35% of total budget, and the tail end of that range usually belongs to projects with long entitlement timelines or complex financing structures.
The 65/80 versus 20/35 split isn’t arbitrary. It shifts based on project type, complexity, and how much preconstruction work is required before you can break ground.
A hypothetical $2 million ground-up build might allocate $1.5 million to hard costs and $500,000 to soft costs, front-loading a sizable chunk of that soft-cost figure into the first three months before construction even starts.
| Factor | Hard Costs | Soft Costs |
|---|---|---|
| Predictability | High (unit-rate based) | Lower (fee and timeline dependent) |
| Timing | Concurrent with construction | Front-loaded, some post-completion |
| Lender verification | Third-party inspection | Invoice or milestone documentation |
Statistic Callout: On a typical project, hard costs represent 65% to 80% of the total budget, which means soft costs, at 20% to 35%, still add up to hundreds of thousands of dollars on a mid-size build. Treat that range as a floor for planning, not a ceiling.
Soft-cost forecasting fails most often because owners treat it as an afterthought to the hard-cost budget, rather than its own line item with its own risk profile.
Start with separate contingencies. The Project Management Institute’s guidance on risk contingency distinguishes contingency reserve, which covers identified risks and sits under the project manager’s control, from management reserve, which covers unknowns and sits with upper management. Apply that same logic here: your hard-cost contingency and soft-cost contingency should be tracked and drawn independently.
Four tactics keep soft costs under control:
Interest reserves deserve special attention. When soft-cost delays push out your construction timeline, financing interest keeps accruing regardless. A permit delay of sixty days doesn’t just cost you the permit consultant’s extra invoice; it costs you two extra months of loan interest on the entire facility. That compounding effect is why soft-cost overruns often hurt profitability more than an equivalent hard-cost overrun does.
Pro Tip: Present your monthly soft-cost reconciliation to your lender proactively, even when they don’t ask for it. It builds the kind of track record that speeds approval on your next draw request, and on your next project entirely.
Not every line item sorts cleanly into one bucket. Built’s analysis of classification disputes points to general conditions as the single most contested category, and that tracks with what shows up in most funding-control disputes.
General conditions, things like temporary fencing, site supervision, and portable toilets, can reasonably sit in either category depending on how your contractor structures the schedule of values. Contingency reserves split the same way: a hard-cost contingency covers construction risk and is typically controlled by the general contractor or project manager, while a soft-cost contingency covers design, permitting, and financing risk and usually stays with the owner or developer.
Overhead follows a similar split. Field overhead (on-site supervision, temporary utilities) usually gets treated as a hard cost. Home-office overhead (corporate accounting, executive time) almost always classifies as soft.
The fix isn’t a universal rule. It’s documentation:
Lenders don’t fund hard and soft costs the same way, and understanding that difference speeds up your money.
Hard-cost draws typically require third-party inspection before release. An inspector visits the site, confirms the work matches the draw request, and signs off before funds move. That cadence usually follows construction milestones: foundation, framing, mechanical rough-in, and so on.
Soft-cost draws work differently. Lenders generally fund against paid invoices or signed milestone documentation, not physical inspection, since there’s no site work to verify. Some lenders require the borrower to fund early soft costs with equity before the loan facility kicks in, then reimburse through an interest reserve carved out of the loan itself.
To keep your draws moving, prepare a package that includes:
Pro Tip: Submit your draw package a few days ahead of your lender’s stated review window. Loan officers batch-process draws, and being early in the queue often means the difference between funding this week or next.
The mistake I see most often isn’t a bad hard-cost estimate. Contractors are generally disciplined about unit pricing. It’s the permit timeline and the interest reserve that get lowballed, almost every time, because both feel abstract until they’re not.
If you take one habit from this article, make it this: build a soft-cost contingency that’s separate from your hard-cost reserve, and reconcile it monthly against actuals, not just against your original budget projection.
— Daly Kay DiNatale
Soft costs create the exact kind of cash-flow gap that traditional lenders struggle to fund quickly: a permit delay here, an extended consultant engagement there, and suddenly you’re carrying costs your original draw schedule never anticipated. That’s where a construction loan with a built-in interest reserve earns its value. It covers the financing gap while your soft-cost timeline stretches, so you’re not scrambling for emergency equity mid-project.
A direct private lender backed by a family office, with a proven track record of closed loans and strong industry ratings. Closings are often fast, completing in days rather than weeks, due to in-house underwriting without layers of approval typical in traditional bank financing. Whether you’re financing a ground-up construction project with a long preconstruction soft-cost runway, or you need a fix-and-flip loan that accounts for renovation soft costs like permits and design fees, our loan programs are structured with the timing gaps in mind. If financing interest and soft-cost delays are already stretching your project thin, a hard money bridge loan can cover the gap while you finish the job. Reach out to discuss your project’s numbers, and we’ll walk you through what a tailored structure looks like for your specific timeline.
Common soft costs include architecture and engineering fees, permits, legal fees, insurance, loan interest and origination fees, project management, and marketing or lease-up costs for income-producing properties.
Most construction budgets break down into hard costs, soft costs, land or acquisition costs, and contingency reserves, with hard and soft costs making up the bulk of the working budget.
A soft cost is any construction-related expense that isn’t tied to physical building work, covering design, permitting, financing, legal, and administrative services that enable a project to proceed.
Soft costs typically run 20% to 35% of a total construction budget, with the higher end more common on complex commercial or multifamily projects with long entitlement timelines.
