November 1, 2026
Written By: David DiNatale, Esq
A hard money loan is short-term financing secured by the property itself, and it is one of the few ways to buy and repair a house that a bank will not touch. Lenders in this space underwrite the deal: what the property is worth today, what it will be worth once repaired, and how you plan to exit. Your credit score and tax returns matter far less. This guide explains how that works for distressed properties, what it costs, what to prepare, and where the risks sit.
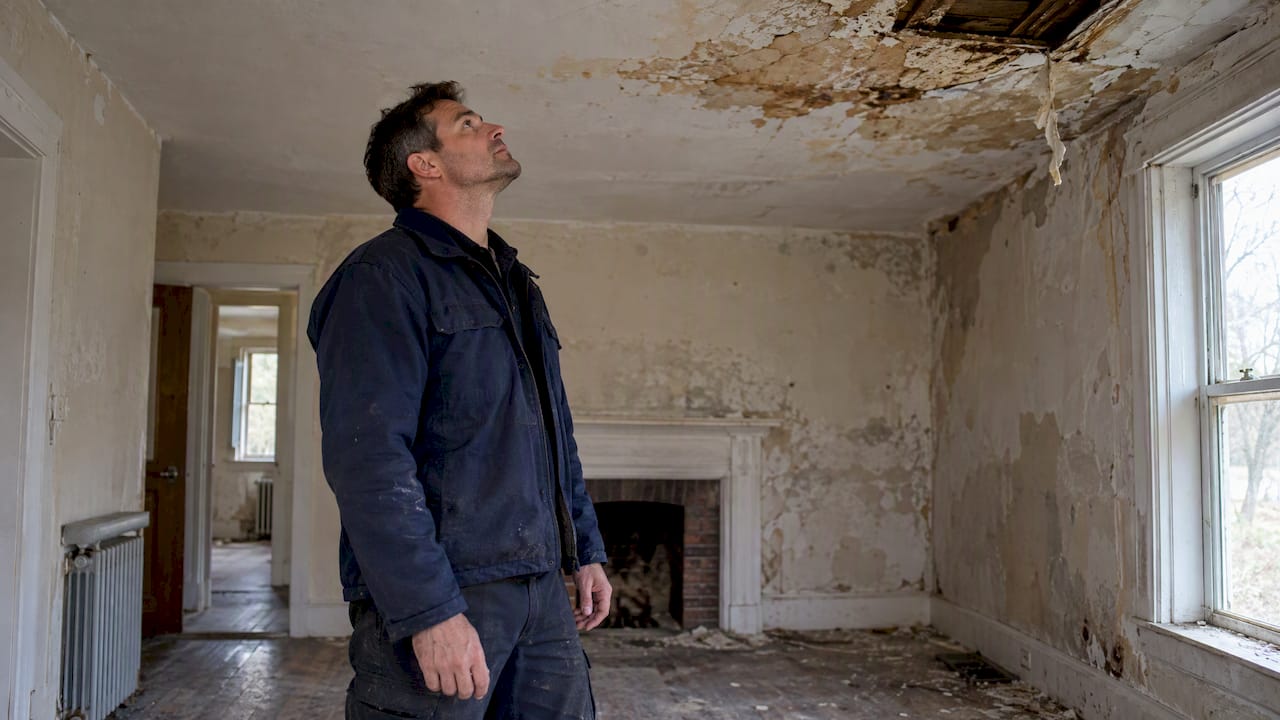
A distressed property might have a failed roof, an outdated electrical panel, water damage, a stalled renovation, or a past foreclosure. Conventional lenders generally need a habitable, appraisable house. Industry coverage in Scotsman Guide makes the same point: a bank will almost always fund a file that meets its underwriting, and the trouble starts when the borrower or the property falls outside those narrow criteria. That is where private capital steps in.
The difference is what gets underwritten. A bank looks backward at your income and the house as it stands. A direct private lender looks forward at the finished product. That is why a house that cannot qualify for a mortgage today can still be a sound loan: the collateral has a clear path to a higher value.
Speed matters just as much. Distressed deals, whether auction purchases, estate sales, or motivated sellers, often close on the seller’s timeline. Our guide to why hard money closes faster covers the mechanics, and our 5 to 14 day borrower checklist lists what to have ready.

Three figures drive almost every distressed-property loan.
| Figure | What it means | Why it matters |
|---|---|---|
| Purchase price | What you pay the seller | Sets your cost basis and the acquisition amount |
| As-is value | What the property is worth today, damage included | The lender’s floor: the value it would recover against |
| After-repair value (ARV) | Projected value once the work is done | Shows the room for profit and the strength of the exit |
As one private lender explains in a fix-and-flip primer, the ratios are simple: acquisition loan-to-value is the loan divided by the current as-is value, so a $100,000 loan on a $200,000 property is 50%. We cite it for the arithmetic only. Terms, leverage and rates vary by lender and by deal, so treat any example as an illustration, not a quote.
Most distressed purchases are funded in two parts: an amount at closing for the acquisition, and a renovation holdback released as work is completed. The loan is repaid when you sell or refinance.
Say you find a four-bedroom house listed at $310,000 that needs a roof, HVAC, kitchen and flooring. Comparable renovated homes nearby sell around $480,000. Your itemized budget is $95,000.
If the answer is thin, adjust the deal before you apply. Renegotiate the price, trim the scope, or shorten the timeline.
The fastest way to slow a distressed-property loan is a vague scope of work. Appraisal practice leans the same way: guidance on REO appraisal reporting notes that repair estimates should be defensible and itemized rather than lumped, and that a clear repair grid covering systems such as HVAC, foundation and mechanical helps justify the gap between as-is and as-repaired value.
A lender-ready budget has:
Documentation habits from other repair fields translate well. For example, a roofing contractor explains why insurers require a written repair estimate, and the same logic applies here: written, itemized figures remove doubt for whoever is paying.
Private capital costs more than a bank mortgage, and you should price it that way. The real comparison is not against a mortgage you cannot get, but against what the deal earns and what a lost deal costs you.
Our published pricing, as listed on our site:
| Program | Published interest rate | Best fit |
|---|---|---|
| Hard Money Loan Program | 9.99-12.49% | Acquisitions and bridge situations |
| Fix and Flip Program | 9.00-11.99% | Buy, renovate, sell |
| Ground Up Construction Program | 8.99-10.99% | Teardowns and new builds |
| Rental DSCR Loan Program | 6.50-8.75% | Long-term hold after stabilizing |
Origination fees run 1.50-3.00%. Your actual rate and fee depend on the deal and the borrower. When comparing offers, add up the whole cost: interest, origination, draw fees, appraisal and legal costs, and any extension fee. Our article on evaluating hard money lender terms walks through the line items.
A practical test: model your profit at the full interest rate and the highest fee, with the project running two months longer than planned. If the deal still works, the financing is not the risk.

Approval is deal-first, but it is not blind. Expect the lender to review:
Our breakdown of the top ten approval factors goes deeper on each, and when hard money beats a conventional loan shows eight situations where the speed is worth the price.
Everything above assumes an investment property. If you plan to live in the distressed house, the rules change. Based on a 2026 guide to hard money on primary residences, these loans fall under Dodd-Frank and CFPB ability-to-repay rules that require income and asset verification, so many hard money lenders avoid them. Those that do lend usually want substantial equity and a documented exit, such as a sale contract or refinance letter. If you are in this position, speak with a licensed mortgage professional and, where needed, a real estate attorney about your specific situation before signing anything.
It is also worth knowing the downside risk of any short-term, high-rate loan. A news report from the San Francisco Chronicle’s SFGate described a landlord with damaged credit who turned to hard money to rehab rental properties after banks said no. The lesson holds today: the loan is a tool for a project with a defined end, not a fix for a cash flow problem with no exit.
We are a direct lender backed by a family office, and we have closed over $1 billion in loans. Across that volume the pattern is consistent: the deals that go smoothly are the ones with a clear plan, an itemized budget and a realistic exit. A distressed property is not a red flag to us. It is often where the best margin sits.
Because our capital is discretionary, we can structure loans around the project instead of forcing it into a template, and we can close in days when a seller is waiting. That includes projects other lenders decline, from heavy rehabs to ultra luxury homes over $10 million. Our advice to borrowers is simple. Talk to us before you are under contract, show us your numbers honestly, and build in a cushion. We would rather help you adjust a deal at the start than see it strained at the end.
— Daly Kay DiNatale
If you have a distressed property under contract or in view, our Fix and Flip Program covers purchase and renovation funding, and our Hard Money Loan Program handles bridge and acquisition situations. We lend to investors, developers and builders, with a particular focus on Florida, and we also serve borrowers nationwide. See what we have funded on our projects page, or contact us through our main site with your address, price, repair budget and exit plan.
Yes, in many cases. Hard money lenders focus on the property’s value and your renovation plan, so condition is not an automatic disqualifier. Expect to provide an itemized repair budget and photos, and expect repair funds to be released in stages.
It varies by lender, deal and borrower. Our published ranges are 9.99-12.49% for the Hard Money Loan Program and 9.00-11.99% for the Fix and Flip Program, plus origination fees of 1.50-3.00%. Always compare the total cost, including fees and extension terms, not only the rate.
A property with enough value to secure the loan, a clear exit strategy, cash for the down payment and closing costs, and a credible budget. Experience helps but is not always required. Our requirements checklist lists the documents to gather.
It refers to IRS imputed interest rules under IRC §7872, not to real estate lending. For loans under $100,000 between individuals, taxable imputed interest is capped at the borrower’s net investment income, and is zero if that income is $1,000 or less. It does not apply if the money buys income-producing assets, so ask a CPA before relying on it.
