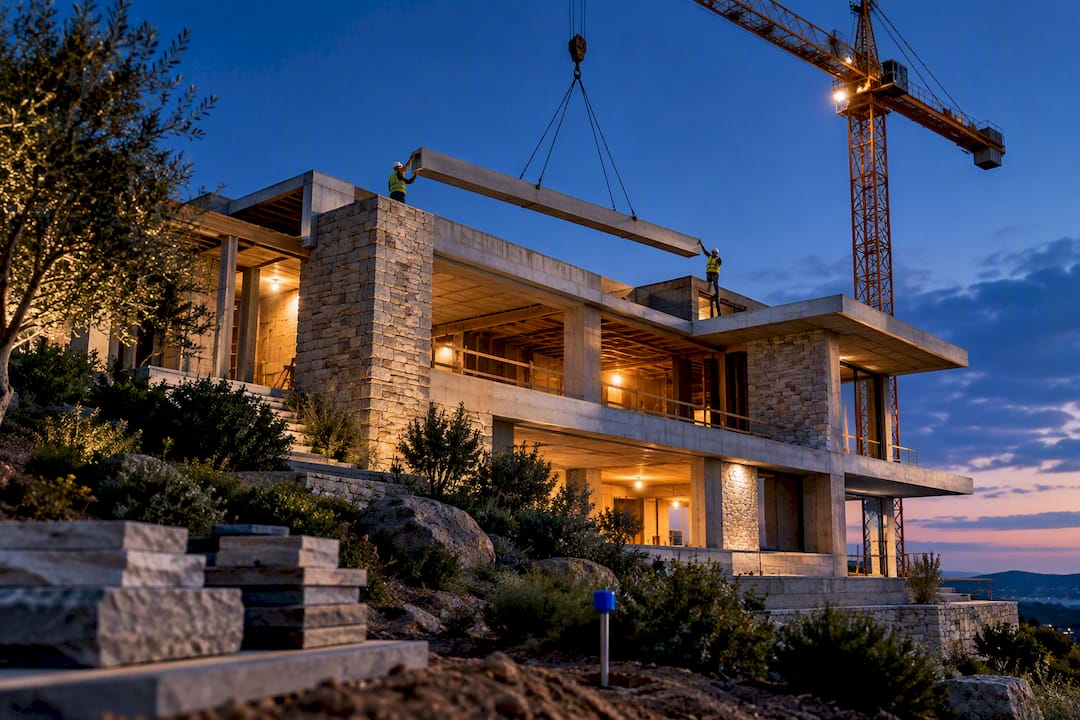
Most luxury custom builds belong in one of two structures: a single-close construction-to-permanent loan for borrowers who want rate certainty, or a jumbo construction loan paired with strong liquidity for those who can qualify at a bank. When a project exceeds $10 million, moves fast, or involves a design bank underwriters won’t touch, a private lender becomes the practical alternative. Whichever route fits, start the same way: lock your architectural plans, a fixed-price general contractor agreement, and 12 to 24 months of PITI reserves before you call a lender.
- Private lenders are often the only option for luxury projects exceeding 10 million dollars or for fast-moving builds with complex designs that banks won’t touch.
- Meeting lender requirements involves providing at least 700 credit scores, 12 to 24 months of liquid reserves, fixed-price contracts, and detailed engineered plans.
- Contingency reserves for luxury builds typically range from 15% to 20%, double the standard on conventional projects, to cover soft costs and unexpected site conditions.
- Construction draws are phased, inspected by third parties, and delays often stem from change orders, incomplete paperwork, or inspection failures.
- Total financing costs can reach 250,000 to 350,000 dollars on a 4 million dollar loan, including fees, inspections, appraisals, and the interest reserve.
Luxury home construction financing splits into five practical lanes, and picking the wrong one costs you either flexibility or money. Standard mortgage limits don’t stretch far enough for most custom estates. Conforming loan limits sit near $806,500, with high-cost-area ceilings that can exceed one million dollars, so anything above those thresholds gets treated as jumbo underwriting with tighter documentation and manual review.
If you already own the land free and clear, a two-close structure can lower your total borrowing need. If you’re financing the lot too, that debt affects your debt-to-income ratio on the construction loan that follows.
Jumbo construction underwriting is manual, not automated, which means every document gets read by an actual underwriter rather than run through an algorithm. That works in your favor if your file is clean and against you if it’s disorganized. Build your package around these seven items:
Pro Tip: Season your reserve funds for at least 60 days before applying. Underwriters flag large, recent deposits, and unexplained cash movement is one of the fastest ways to stall a jumbo file.
Luxury projects run on bigger contingencies than standard construction, and lenders expect to see that cushion before they’ll fund the loan. A typical single-family build might carry a 5% to 10% contingency. Luxury custom homes routinely need 15% to 20% set aside for the same purpose, and lenders reviewing your budget will ask why it’s missing if it isn’t there.
Luxury custom builds commonly plan contingency reserves of 15% to 20%, roughly double the 5% to 10% standard on conventional projects, according to industry cost data.
Soft costs deserve their own line items, not a vague buffer buried inside “miscellaneous”:
Interest reserves work differently than most borrowers expect. Instead of paying loan interest out of pocket each month during construction, the lender finances that interest inside the loan itself.
Site conditions can blow past even a generous contingency. Soil remediation, deep pile foundations on unstable ground, and custom infinity pools or water features regularly add six-figure surprises that a standard contingency doesn’t fully absorb.

Construction loans release money in draws tied to completed, inspected milestones, not in one lump sum at closing. You pay interest only on funds actually disbursed, which keeps carrying costs lower early in the build when little cash has gone out the door.
Keeping documentation staged in advance, submitting invoices the same week work finishes, and writing clear change-order language into your GC contract will keep draws moving. Our breakdown of how construction loan draws work covers the inspection sequence in more detail if you want the mechanics before your first draw request.
Plan on 18 to 30 months from signed contract to final certificate of occupancy, with design and permitting alone often consuming four to eight months before construction even starts. Sitework and foundation typically run six to ten weeks, vertical construction stretches 8 to 14 months depending on square footage and complexity, and finish work on high-end interiors regularly adds another three to five months beyond what a standard home would need.
ARB or HOA approval cycles, geotechnical surprises, and backordered specialty subcontractors are the three delays that show up most often, and each can add one to three months on its own. A six-month delay on a jumbo loan doesn’t just push your move-in date. It can exhaust your interest reserve early and force a rate-lock extension, which typically carries its own fee.
Not every lender that offers construction loans understands luxury builds, and that gap shows up fastest during underwriting, not at application. Evaluate lenders on five things: product fit for your loan size, actual experience closing luxury projects, speed to close, how they structure interest reserves, and how their draw and inspection workflow actually runs.
Pro Tip: If a lender can’t answer your interest-reserve question specifically, in dollars, for your loan size, that’s a sign they haven’t underwritten many luxury builds.
Red flags worth walking away from: vague fee structures, no willingness to vet your builder before quoting terms, no subject-to-completion appraisal process, or loan-to-value promises that sound too generous for a manually underwritten jumbo file. When a project needs speed, a creative structure, or financing beyond what a bank’s guidelines will support, that’s exactly the gap a private lender like Capital Funding is built to fill.
If you chose a single-close C2P loan, conversion happens automatically once the lender issues a final certificate of occupancy and confirms the project matches the appraised, as-completed value. There’s no second closing, no new credit pull in most cases, and no additional set of closing costs. Your interest-only construction payments simply roll into fully amortizing principal-and-interest payments at the rate locked back at your original closing.
Two-close borrowers face an actual second transaction. Once construction wraps, you apply for a new permanent mortgage, which means a fresh credit check, updated income documentation, and a new appraisal, this time valuing the finished home rather than the plans. The lender pays off the construction loan balance with proceeds from the new permanent loan, and you close on new terms, which could be better or worse than the rate you’d have locked at the start, depending on where rates moved during your build.
Either path requires final lien releases from your general contractor and subcontractors, confirming no outstanding claims against the property. Skipping this step, or letting paperwork lag, is a common reason conversions stall even after construction itself is finished. Borrowers using a private construction loan sometimes plan the conversion differently. Many refinance into a conventional or jumbo permanent mortgage once the home is complete and stabilized, using the finished appraisal to secure long-term financing at a lower rate than the construction loan carried.
Once your luxury home is complete, refinancing typically means moving out of a higher-rate construction or private loan and into permanent financing sized against the finished home’s appraised value. Three paths show up most often for luxury borrowers.
A rate-and-term refinance into a jumbo permanent mortgage makes sense if your construction loan carried a private-lender rate and your finished home appraises well above the loan balance, giving you room to qualify for standard jumbo pricing. A cash-out refinance lets you pull equity out of the completed home, useful if you funded part of construction with personal liquidity you’d like to replace. A DSCR-style refinance applies if the finished property will operate as a rental rather than a primary residence, qualifying based on the property’s income potential rather than your personal income documentation.
Timing matters more on luxury refinances than standard ones. Lenders generally want the home fully complete with a final certificate of occupancy, and some want to see a stabilization period, often three to six months, before refinancing a highly customized property they haven’t seen generate comparable sales yet. Rushing a refinance before the appraisal reflects true market value can leave real equity on the table.
The interest rate is only one line on the invoice. A full cost breakdown on a luxury construction loan includes origination fees, inspection fees tied to each draw, appraisal costs for the subject-to-completion valuation, the interest reserve itself, and potential rate-lock extension fees if the build runs long.
On a $4 million construction loan, a 2% origination fee alone runs $80,000, before a dollar of interest accrues. Add draw inspection fees across eight to ten milestones, an appraisal in the $3,000 to $5,000 range, and the interest reserve calculated earlier, and total financing costs beyond the purchase price of materials and labor can easily reach $250,000 to $350,000 on a project this size. Getting a full fee disclosure in writing before you sign is the single best way to avoid a surprise at closing.
The path from application to final payoff runs through six distinct stages, and knowing what happens at each one keeps you from getting blindsided.
Stage one: pre-application prep, typically four to six weeks, where you gather tax returns, season reserve funds, finalize architectural plans, and lock in a fixed-price contractor agreement. Stage two: application and underwriting, running two to six weeks for a bank jumbo loan or as little as a few days for a private lender, where the file gets reviewed and the subject-to-completion appraisal ordered. Stage three: closing, when loan documents get signed and the interest reserve is established.
Stage four: construction and draws, the longest phase at 12 to 24 months, where funds release against inspected milestones. Stage five: completion and conversion, when the certificate of occupancy triggers either automatic conversion to a permanent mortgage or a second closing on new permanent terms. Stage six: repayment or refinance, where you either make standard mortgage payments on the converted loan or refinance into different permanent financing based on the completed home’s value.

Each stage has its own documentation demands, and the biggest timeline risk sits in stage four, where change orders and inspection delays do the most damage to your schedule.
Approval on a luxury construction file comes down to how well your paperwork answers questions before an underwriter has to ask them. Four moves consistently improve approval odds on high-value builds.
Present a complete, fixed-price GC contract rather than a cost-plus agreement, since underwriters read cost-plus structures as open-ended risk. Season your liquid reserves for a minimum of 60 days, because large recent deposits trigger additional scrutiny that can add weeks to your timeline. Bring fully engineered plans, not conceptual renderings, since a subject-to-completion appraisal needs enough detail to support a credible valuation. Choose a builder with a documented track record on comparable luxury projects, since lenders weigh contractor risk almost as heavily as borrower risk on custom high-end builds.
Borrowers with irregular income, business owners and retirees especially, often strengthen their file by presenting asset-depletion calculations alongside traditional income documentation, giving underwriters two ways to qualify the file instead of one.
Down payment requirements on jumbo construction loans typically run 20% to 30% of total project cost, higher than the 3% to 20% range common on conventional mortgages, because lenders treat ground-up luxury construction as inherently higher risk than purchasing a finished home. That down payment usually needs to be liquid and seasoned, not pledged against other assets.
Reserves are separate from the down payment and often catch first-time luxury builders off guard. Lenders commonly require 12 to 24 months of PITI held in reserve, meaning principal, interest, taxes, and insurance on the eventual permanent mortgage, sitting untouched in an account the lender can verify. On a $6 million home with an estimated $35,000 monthly PITI once complete, that reserve requirement alone could mean $420,000 to $840,000 in additional liquidity beyond your down payment and construction contingency.
The interest reserve, covered earlier as part of your budget, is financed within the loan itself and doesn’t require separate cash. Add these three pools together, down payment, PITI reserves, and contingency, and you’ll have a realistic picture of total liquidity a lender expects before approving your file.
Bank underwriting works fine until a project doesn’t fit a template, and most true luxury builds don’t. Capital Funding operates as a private lender backed by a family office, which means decisions get made by people evaluating your actual project, not a rate sheet built for tract housing. That structure lets us close hard money loans in days rather than months, and it’s why we’re able to finance ultra luxury single-family homes over $10 million that conventional bank guidelines simply won’t touch. With over $1 billion in closed loans and an A+ BBB rating, our track record reflects a straightforward approach: bring us engineered plans, a fixed-price builder contract, and clear reserves, and we move fast.
— Daly Kay DiNatale
If your project needs speed, a nonstandard structure, or financing above what bank guidelines allow, Capital Funding’s Ground Up Construction Program is built specifically for developers and builders taking on high-value custom homes. For borrowers facing a tighter timeline or a project banks have already declined, the Hard Money Loan Program offers the same direct, family-office-backed capital that closes in days instead of months.
Before you reach out, put together the four items that speed up every conversation: fully engineered architectural plans, a fixed-price general contractor agreement, 12 to 24 months of PITI reserves documented and seasoned, and a construction schedule with your builder’s references attached. Projects over $10 million should also review our guide on closing a jumbo luxury loan before the first call, since it walks through exactly what we look for on files at that size. Reach out through our services overview to start the conversation, and we’ll tell you within days whether your project fits, not weeks.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Luxury construction loans add reserve requirements on top of income qualification, so the income figure alone doesn’t tell the full story.
During construction, you typically pay interest only on the amount actually drawn, so early payments start low and rise as more funds get disbursed. Once the loan converts to a permanent mortgage or the full amount is drawn, expect a fully amortizing payment based on the locked rate.
Large national banks such as U.S. Bank publish standard construction loan products with one-time close and draw-based disbursement structures common across the industry. For luxury and jumbo projects that fall outside standard bank guidelines, private lenders like Capital Funding fill the gap banks won’t cover, particularly on projects above $10 million.
Jumbo construction loans typically require 20% to 30% down, higher than the 3% to 20% range common on standard conventional mortgages, because lenders treat ground-up construction as higher risk. Private construction lenders sometimes structure lower down payment requirements in exchange for stronger reserves or a higher rate, so the exact figure depends on the lender and loan structure.
Capital Funding can close hard money and construction loans in days rather than the weeks or months typical of bank underwriting, provided the borrower has engineered plans, a fixed-price builder contract, and documented reserves ready at application.
