November 1, 2026
Written By: David DiNatale, Esq
Underwriting exceptions are permitted on a case-by-case basis when documented compensating factors and proper approvals exist. Banks follow Federal Reserve interagency guidance, and Fannie Mae runs formal waiver processes such as CVAS, SLW and PEW. At Capital Funding, we are a private lender that structures documented exceptions for projects outside the bank box.
- Banks generally should not originate single family mortgages above 90% LTV without credit support such as mortgage insurance; exceptions require compensating credit factors.
- Lenders must identify loans above supervisory LTV limits and report aggregate totals to their boards at least quarterly; totals near capital limits draw scrutiny.
- Fannie Mae’s single loan waivers cover one loan and one named issue, while project waivers are reviewed individually and may carry conditions before delivery.
- Tie the deviation to verified income, reserves, collateral, insurance, appraisal support, or a project budget, and label exhibits in a rationale limited to one page.
A real estate underwriting exception is a departure from a lender’s written underwriting standards or from supervisory limits. The loan is not a mistake or a favor. It is a deliberate decision, backed by a written rationale, that the risk remains acceptable despite the deviation.
Most real estate loan exceptions fall into a handful of familiar categories:
Consider two short scenarios. A lender might approve a single-family loan above 90% LTV because mortgage insurance backs the top slice of the balance. Or a bridge or construction loan might fall outside certain ability-to-repay rules altogether, because Fannie Mae’s loan eligibility rules classify some loans as exempt and treat them differently. In both cases the exception exists on paper, and the file explains why it is sound.
Recognizing your deal in this list is the first step. The rest of the process is about proving it deserves the waiver.
Federal supervisors do not ban exceptions. They control them. Under interagency guidance on high-LTV lending, banks generally should not originate single-family mortgages above 90 percent LTV without credit support such as mortgage insurance. Individual exceptions remain permitted when other credit factors support the loan.
The tracking rules are what give the guardrail teeth. Per the interagency guidelines on policies, lenders must identify loans that exceed supervisory LTV limits and report aggregate totals to the board of directors at least quarterly. Aggregate limits are tied to capital, and a lender that approaches them draws closer examiner attention.
Why such tight oversight? One exception is a judgment call. A pattern of them is a portfolio risk. Examiners read volume and repetition as a warning sign, so lenders keep written justifications, track every deviation, and cap how many they will grant.
Collateral valuation gets the same scrutiny. The interagency appraisal and evaluation guidelines call for elevated review of higher-risk transactions and often a full appraisal in place of a simplified evaluation. The underlying standard, found in 12 CFR § 160.101, asks that loans be prudently underwritten around the borrower’s capacity to repay, the property’s value, secondary sources of repayment and any additional collateral.
For you, the takeaway is practical. A regulated lender that says yes to an exception has to defend that yes in writing, repeatedly, to its own board and its examiners.

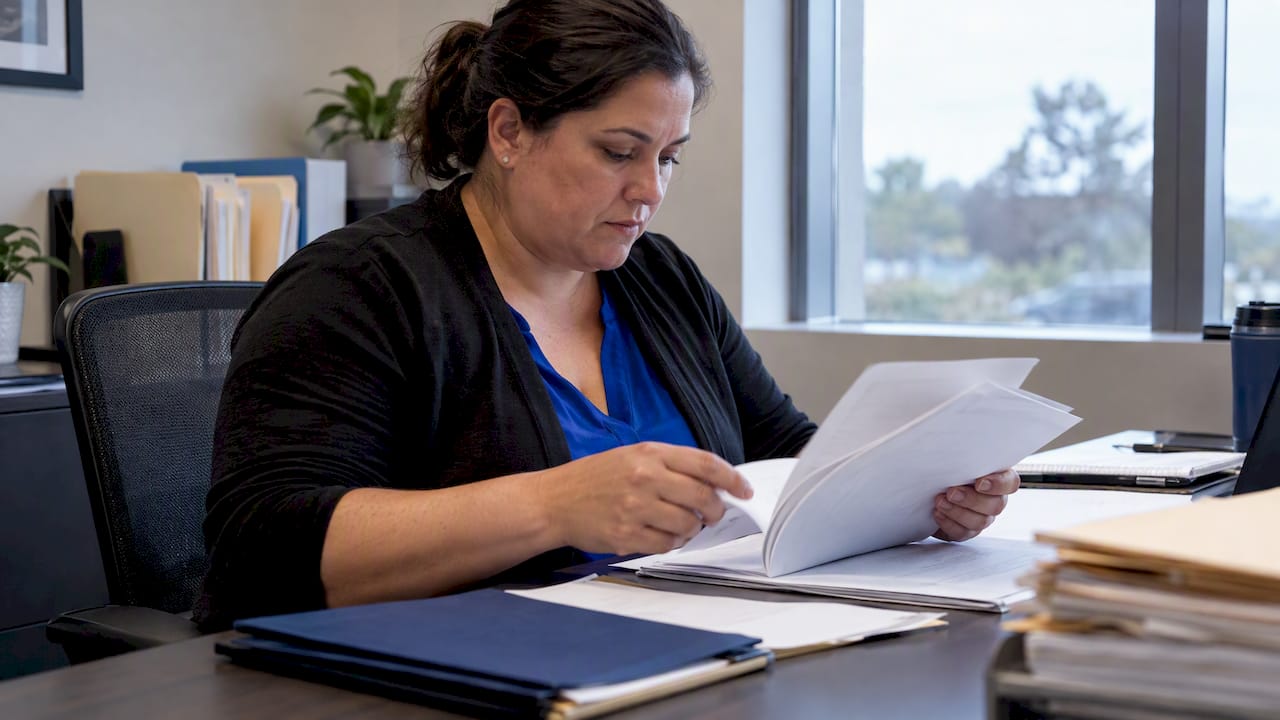
Approval follows a chain of custody. Inside a lender, an exception starts with a loan-level written justification, moves up to a credit committee or senior approver, and is logged for periodic reporting to the board. Records are retained so the decision can be reviewed long after closing.
Loans destined for the secondary market add a second layer. Fannie Mae documents formal waiver routes in its Credit Variance Administration System, where a lender categorizes the request, explains the deviation and submits a risk profile that includes compensating factors. For projects, Fannie Mae’s special considerations guidance allows requests for projects that miss eligibility requirements, judged one project at a time.
A few practical constraints shape how these waivers work:
The same discipline shows up in private lending, minus the secondary-market paperwork. Our approvals still require a written rationale and sign-off, because a documented decision protects everyone at the table.
A lender approves an exception when strengths elsewhere in the file outweigh the deviation. Your job is to make that case easy to read. The strongest compensating factors are verified income and liquidity, additional collateral or a guarantee, mortgage insurance or a government guaranty, a well-built project pro forma, and a clean payment history.
Build your request in this order:
Pro Tip: Keep the written justification to one page and label every compensating factor with the exhibit that proves it. Reviewers approve what they can verify quickly.
Our own approval criteria work the same way. For a closer look at what private lenders weigh, read our breakdown of hard money lender approval criteria, and for the construction side, see how construction loan underwriting works for developers.
Exceptions are a tool, not a shortcut. Used with discipline, they let credit reach good borrowers whose deals do not fit a template: the investor with a strong track record and an unusual asset, or the developer whose project is sound but unconventional. Documentation and board oversight protect the lender and the borrower alike, because a clean file is the best defense when anyone looks back at the decision.
The flip side deserves equal weight. A lender that leans on exceptions as a habit is signaling weak standards, and regulators read it that way. Private lenders fill a legitimate gap here, since a documented, fast-closing structure can serve deals that fall outside bank boxes without pretending the deviation does not exist.
— Daly Kay DiNatale
When a deal falls outside standard boxes, we treat the exception as a decision to document, not a favor to grant. As a direct lender backed by a family office, we can close quickly, and we tailor structures for projects that conventional lenders pass on, including luxury homes.
Here is what that looks like in practice:
If your deal needs an exception, start your loan application and tell us what makes the project strong.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Yes, but only case by case and only with documentation. Federal interagency guidance permits individual exceptions to supervisory LTV limits when other credit factors support the loan. Lenders must track and justify each one.
Lenders commonly waive or flex LTV limits, documentation depth, occupancy or property type rules, and seasoning requirements. What is waived depends on the lender’s policy and, for sold loans, on what the buyer will accept. Each waiver should be tied to a specific compensating factor.
Fannie Mae reviews waivers through formal systems such as the Credit Variance Administration System. Lenders submit an explanation, a risk profile with compensating factors and supporting files. Approvals are specific to the loan and can carry conditions.
Yes. Under the interagency guidelines, lenders report aggregate exception totals to the board at least quarterly, and heavy aggregation raises supervisory scrutiny. Repeated patterns of exceptions tend to draw examiner attention.
Verified income and reserves, additional collateral or a guarantee, a strong appraisal and a realistic project budget help most. A short written justification that ties each strength to the deviation makes the request easier to approve.
